See how a reverse mortgage could help you stay in your home in Sun City, remove a monthly mortgage payment or add to your retirement income. Mark Boeck explains what you may qualify for and what it costs.
Retirement Mortgage Advisor
NMLS #107448 DRE #01845041
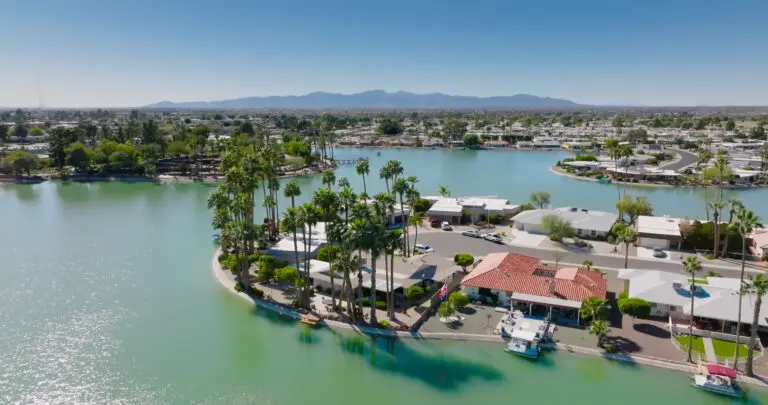
Turn part of your equity into cash, monthly payments or a line of credit, and keep living in your Sun City home. First year draws are limited, and Mark explains how.
If you still have a mortgage, a reverse mortgage can pay it off. No monthly principal and interest payment is required while you live in the home.
You keep the title and stay in your home. Keep paying property taxes, insurance, HOA dues and upkeep, and the loan stays in good standing.
Take a lump sum, monthly payments, a line of credit or a mix. With a HECM, any unused line of credit grows over time, so more is available later.
You never owe more than your home is worth. When the loan is repaid, your heirs keep any equity left after the balance is paid.
Mark Boeck explains what you could receive, what it costs and the alternatives in plain English, so Sun City homeowners can decide with confidence.
Mark Boeck, Retirement Mortgage Advisor (NMLS #107448), has more than 25 years in mortgage lending and helps homeowners in Sun City and across Arizona. Working with Mark means:
Explore how a reverse mortgage can help you eliminate your monthly mortgage payment, access home equity, or fund your retirement goals. Mark Boeck is here to guide you. Book a call to see what you qualify for and get answers tailored to your needs.
A reverse mortgage lets homeowners in Sun City access the equity in their home without making monthly mortgage payments. Available to those aged 62 and older, this loan allows you to convert part of your home’s value into tax-free funds. The loan is repaid when the home is sold or no longer your primary residence.
To qualify in Sun City, you must be at least 62 years old, own your home (or have a significant amount of equity), and live there as your primary residence. Your property must meet FHA guidelines, and you’ll complete a required counseling session to ensure you understand the loan structure.
If you still have a traditional mortgage, a reverse mortgage can be used to pay off the balance, removing the need for monthly payments. This frees up your cash flow so you can enjoy retirement in Sun City with more peace of mind.
Yes. Sun City homeowners often use reverse mortgages to tap into built-up equity without selling or moving. Whether you want a lump sum, monthly payout, or line of credit, this option gives you control over how and when you receive the funds.
Absolutely. With a Home Equity Conversion Mortgage for Purchase (HECM for Purchase), you can buy a new home in Sun City using a reverse mortgage, allowing you to relocate or downsize without taking on a new monthly payment.
Yes. If you already have a reverse mortgage, refinancing may help you access more equity, improve your loan terms, or add a spouse to the agreement. Mark Boeck can review your current loan and show you your options.
Definitely. Many homeowners in Sun City use reverse mortgages to create a reliable income stream that supports daily expenses, healthcare costs, or simply offers more financial flexibility.
From travel and home renovations to long-term care planning, Sun City homeowners are using reverse mortgages as part of a broader retirement strategy. The funds are flexible and can help you stay financially independent for longer.
Yes. Reverse mortgages are backed by the FHA and come with consumer protections. You remain the homeowner and will never owe more than the home is worth, as long as you meet the basic obligations like taxes and insurance.
Start by booking a call with Mark Boeck. He’ll explain your options, review your eligibility, and help you understand how a reverse mortgage can work for your situation in Sun City.
