A jumbo reverse mortgage is a private loan for higher value Arizona homes. It can lend beyond the FHA limit, so you may access more of your equity with no monthly mortgage payment required.
A privately funded reverse mortgage for higher value homes. It can lend on value above the FHA lending limit, so more of your equity is available.
Age rules vary. Some programs accept borrowers 55 or older in Arizona, while others require 62. You must live in the home, have substantial equity and show you can pay taxes and insurance.
It depends on your home value, your age and current rates. Because jumbo loans go beyond the FHA limit, owners of higher value homes may access more than a HECM allows.
Jumbo loans are not FHA insured, so there is no FHA mortgage insurance premium, but rates are often higher. Some programs also accept condos that are not FHA approved.
Pay off an existing mortgage, update your home, cover healthcare or keep a reserve for later. You still pay property taxes, homeowners insurance and upkeep.
If your home has gained value, moving from a HECM to a jumbo loan may unlock more equity. Mark compares the new costs with the gain before you decide.
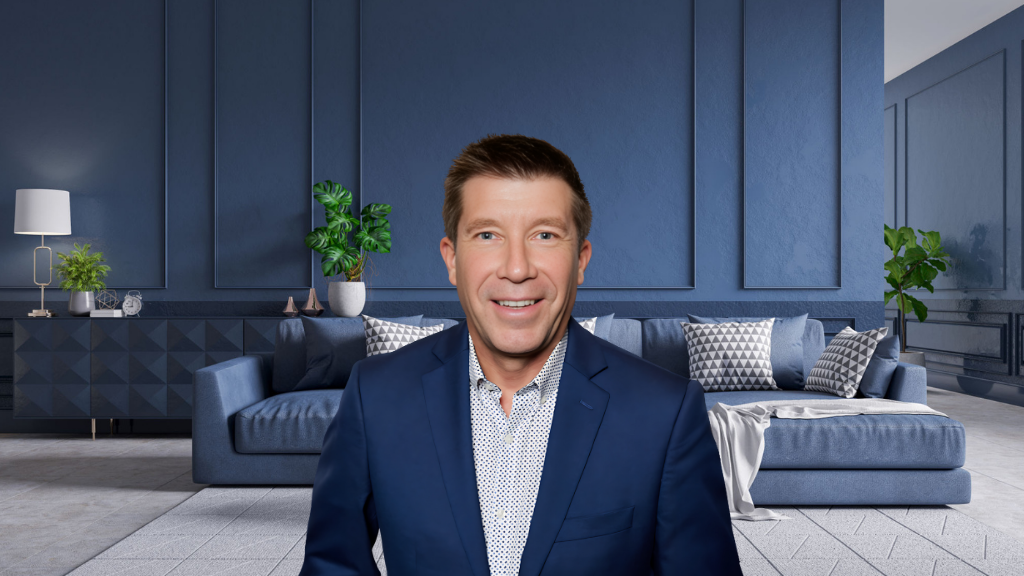
Mark Boeck, Retirement Mortgage Advisor (NMLS #107448), has more than 25 years in mortgage lending and helps owners of higher value Arizona homes compare their options. Working with Mark means:
Thinking about a Jumbo Reverse Mortgage in Arizona? Get clear, honest answers from Mark Boeck, Retirement Mortgage Advisor. Whether you are exploring your options or ready to move forward, these FAQs will help you feel more confident and informed about unlocking greater home equity with a Jumbo loan.
A jumbo reverse mortgage is a private loan for higher value homes. It is not insured by the FHA, so it is not capped by the FHA lending limit and can give owners of valuable Arizona homes access to more equity. No monthly mortgage payment is required, but property taxes, insurance and upkeep continue.
Age and equity rules vary by program. You must live in the home as your principal residence, have substantial equity in a higher value home and be able to keep up with taxes, insurance and upkeep. Mark checks which programs fit your home and situation.
It depends on your home’s appraised value, your age, current interest rates and the program. Because jumbo loans are not capped by the FHA lending limit, owners of higher value homes can often access more than they could with a HECM.
A HECM is insured by the FHA, has a national lending limit and charges FHA mortgage insurance. A jumbo reverse mortgage is privately funded, has higher limits, usually has no FHA mortgage insurance, and its terms, protections and payout options are set by the lender rather than the FHA.
Yes. If your home is worth well above the FHA limit, moving from a HECM to a jumbo loan may give you access to more equity. A refinance brings new costs and different protections, so Mark compares both loans side by side before you decide.
Yes. You keep title and live in the home as your principal residence. You must keep paying property taxes, homeowners insurance and upkeep, and the loan is repaid when you sell, move out permanently or pass away.
Most jumbo programs offer a lump sum, and some also offer a line of credit or monthly payments. Options vary by lender, so Mark explains which payout choices are available for your home.
